Showing posts with label finance. Show all posts

Monday, December 14, 2009

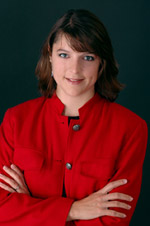
Meet the expert: Julie Asti, CFP

As I mentioned, I attended a Young Women and Money Conference last week. Julie Asti, Certified Financial Planner (CFP), presented a very informative workshop called "What to do before I say I do." I asked her a few questions so that you'd get to know the expert behind the advice and also get a feel for some questions you might want to ask when searching for a CFP to work with (particularly their process, fee policy and certification). 


1) How did you get started?
I got interested in Finance and Investing way back when I first started college as a freshman after NO previous interest in business at all. I’ll be honest, initially it was the lure of big money that got me interested. I decided to major in Finance, Banking and Real Estate and started my career working in financial services. Early on I learned that this career was also personally beneficial – I was learning all there was to know about investing which helped my own financial situation. I worked for really small investment firms, dot com investment firms and really large investment firms and I’ve loved it all.   

2) What do you love most about your job?

I love sharing my knowledge to help other people. I tell people that this is not rocket science, but it is hard and takes time. When I meet with someone, their situation is like a Rubik’s cube to me. I like to analyze their situation to come up with the best advice for their situation and goals. And it is entirely fulfilling to present a plan to someone and see the relief they experience knowing they’ve gotten their situation under control and a solid plan to move them forward.

3) Why should couples consider working with a financial planner?

Couples should definitely do some research before they consider working with a financial planner. The first thing they need to do is talk to each other to see what their goals are and what they’d like to accomplish in working with a planner. I can help them solidify that, but they should be on the same page in coming to see me. With the internet, it is easier than ever to research investment professionals. They should not only use consumer sites like yelp.com, but they should also use professional sites like www.finra.org/brokercheck, or www.sec.gov/investor/brokers.htm, www.corp.ca.gov/about/adviser.asp to see if the professional has any complaints. The sites also provide consumers lists of questions to ask and documents to ask for.

The one thing they should really do is research on how investment professionals are compensated so they understand what they will be charged. Investment professionals need to be compensated just like anyone else, but we have different business models and you should make sure you work with someone who fits your needs.

4) What sets you apart from other financial planners?

To dovetail on that question, I think one thing that sets me apart is my business model.  I’m a Certified Financial Planner (CFP) and Registered Investment Advisor (RIA) with the State of California.  The CFP part means that I have had to go through a university program specializing in financial planning, pass a rigorous test (similar to the Bar exam) and meet experience requirements to carry that designation. I must also adhere to very high ethical standards set forth by the CFP Board.  Personally, it also means that I focus on someone’s entire financial situation, not just their investments. I work with lots of clients and never do any investment work – I help them create a plan to get out of debt, create a plan to help them save for their first home or help them understand the financial implications of getting married or going back to grad school.

The RIA part means that I am not affiliated with a broker/dealer and do not earn investment commissions. This means the only fee I receive is what the client pays me.  Many of my clients choose me because of this. They want to know I’m not recommending an investment that I’ll earn a 10% commission on. If I recommend an investment, it’s because I believe it is the best alternative for their specific situation.

Lastly, I charge an hourly rate for advice. Its pretty straightforward and I’m really up front about my fees. I don’t have any investment minimums or require that I manage client’s money. People come to see me for advice and I provide it for a fee. Pretty simple.

5) Just for fun: what's your favorite part of a wedding?

The reception!  Ok, I do like the ceremony as well when you can see how in love and full of hope and dreams they are – very sweet. But its fun to go to the reception where everyone can just have a good time and lose a bit of the formality and really celebrate the couple and their new life together. Doesn’t have to be fancy at all – just good friends, family and a good time.

Julie can be reached at julie@astifinancial.com or (510) 558-8557. Her website is astifinancial.com. 

Tuesday, December 8, 2009

I'm my own PG & E

I recently attended the YWCA of Berkeley/Oakland's Young Women and Money Conference on December 5. I'll share what to do before you say 'I do' in a later post, but I first wanted to share the great stuff I learned (or reaffirmed), especially since money is such a touchy issue in marriage:

What comes to mind when you think of women and money?

Shoes.
Prince Charming.
I can save later.
I don't have enough.


That last one is sticky. How many times have we heard it, from ourselves or from our friends and family? The reality is, we all do have enough and are in position to be prosperous if we think about money differently.

That's what was so empowering about this conference. We heard from three distinguished and inspiring keynote speakers throughout the day: Veronica Dangerfield (Inspirational Speaker and Marketing Manager at Patelco Credit Union), Valerie Coleman-Morris (former Business Anchor at CNN) and Kathleen Ronald ("Queen of Business Networking" and founder of Speakacular). The overall theme woven through each of their "pep talks" was that we all have the power within ourselves to take control of our money and that saving money is easier than you think -- as long as we put our minds over matter.

For some of us, dealing with money is like dieting. You slip up once and say to yourself, "Well, I screwed up so I guess indulging again today isn't going to make a difference -- I've already lost the battle." To make yourself feel better, you treat yourself to a new purse, a $30 meal, or a pair of jeans "on sale" and charge it to your card. Emotional spending, like emotional eating, is dangerous! Before making any impulsive purchases, ask yourself, do you really need it, or do you want it? Why do I want or need this?

By being honest with yourself, you will be taking the first step towards sound financial health. Even more importantly, if you do make a mistake, don't beat yourself over it. Forgive yourself for missing a credit card payment or opening another store credit card. Many women beat themselves over failure and fall into a vicious cycle of letting the failures pile up instead of looking at mistakes as guidelines to success. It's never too late or too early to start a healthy financial life, so don't sweat the small stuff. Just learn from your mistakes and move on.

Another recurring theme was self-reliance: "Pay yourself first." For every paycheck that you earn, be sure to put a percentage of it directly into a savings account that you cannot easily withdraw from. That way, you can start building your savings without really ever knowing you "had" that money. Or you can start as simply as saving all your loose change or a $1 a day. When you pay yourself first, you are investing in your future financial success. And yes, you can maintain a separate account for yourself from your husband's; open a joint account to pay the fixed expenses but continue to hold onto your personal one.

Valerie Coleman-Morris shared these guidelines, which she called "Muddisms," or pearls of wisdom from the mothers in her life:
  • Be deliberate
  • Set small goals
  • Achieve a them and set bigger ones
  • Learn to function in chaos and you will finish in style
Valerie's tips coupled with Kathleen Ronald's advice to dare to dream, build a team (such as recruiting the support of friends and a certified financial planner)  and have faith, were very inspiring. It all went back to what Veronica Dangerfield called "ashay" -- we've all got the power within to make our dreams come true. If you want to own your own home, build your business, or have a great nest egg when you retire, it's all possible as long as you realize you are your own "PG & E." Money doesn't give you power, rather you give it power to achieve your dreams.

If you missed this conference, don't fret. Go out and get a certified financial planner, open a savings account (separate from your checking), start saving, be conscious of your spending habits, and dare to dream and reach for them. With faith in yourself, you'll begin to live a prosperous life.

Here are some additional resources:
The Thin Pink Line
Practical Money Skills
Jean Chatky's: The Difference

Friday, December 4, 2009

Final thought for the week: money, money, money


{Photo from Life123.com}

Yes, marriage is about love, but what's the number one reason for most strife in a marriage? It's no big surprise -- money.

Earlier this week, I had dinner with a good friend, who's also my personal financial advisor. I missed the Wells Fargo event he had invited me to that featured best-selling author, Jean Chatzky (Make Money, Not Excuses) and I'm kicking myself for it. Chatzky rules for living a prosperous life are common sense (see below), but why is it so hard for us to get?

Jean Chatzky's 4 Rules:

1. Make a decent living
2. Spend less than you make
3. Invest the money you don’t spend
4. Protect the financial world you build so that a disaster doesn’t take it all away from you


My friend asked me what my financial future looked like in 5, 10, and even 20 years out and I was caught off guard. Not because I don't have an idea, but I have yet to build that roadmap -- and obviously now with the input of my future husband!

Tomorrow, I'm going to attend the YWCA's Young Women and Money Conference in downtown Oakland. It's an all-day conference that includes meals, keynote speakers and two breakout sessions (all for $10 with the Young Women Social Entrepreneur 10 for $10 discount). The ones I'm looking forward to are What To Do Before You Say “I Do” and Power Over Plastic: Credit, Cash and Your Brilliant Financial Future. 

Question for all you brides: what are you doing to prepare yourself financially before getting married?

Related Posts with Thumbnails